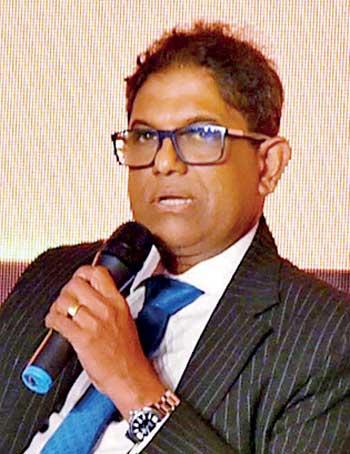
Sri Lanka may face difficulties in attracting fresh private and foreign capital into development banking unless fiscal incentives are introduced to offset the high tax burden on banking profits, Standard Chartered Bank Sri Lanka Chief Executive Officer Bingumal Thewarathanthri has said.
Thewarathanthri, who also serves as Vice Chairperson of the Ceylon Chamber of Commerce, made the remarks during a panel discussion on Sri Lanka’s financial landscape at the 49th Annual Meetings of the Association of Development Financing Institutions in Asia and the Pacific, hosted by DFCC Bank in Colombo.
Rather than focusing solely on who should own a development bank, he said the more fundamental question was why investors would be willing to provide capital to such an institution under the current tax structure.
He pointed to the banking tax burden, which he said can absorb around 50 to 60 percent of profits, arguing that such a level of taxation could make it difficult for a new development bank, a public-private partnership or a development-banking subsidiary of an existing financial institution to attract foreign investment.
Thewarathanthri acknowledged that providing special incentives would not necessarily align with the thinking behind Sri Lanka’s current International Monetary Fund (IMF) programme. However, he noted that other countries had used incentives during the early stages of developing similar institutions before gradually moving towards standard banking tax rates as their financial systems matured.
He also highlighted the scale of Sri Lanka’s small and medium-sized enterprise (SME) sector, noting that the country has more than 160,000 registered companies alongside more than half a million informal businesses. Together, these enterprises provide employment to an estimated 3.5 to 4 million people.
However, Thewarathanthri cautioned that simply increasing the availability of capital would not be enough to strengthen development banking. He argued that lending strategies should be aligned with Sri Lanka’s economic priorities rather than being shaped primarily by the objectives of funding institutions.
He stressed that decisions on which industries, demographic groups and regions should receive development finance need to be based on reliable data.
According to him, lending decisions should not depend on individual preferences or assumptions. Instead, financial institutions should use data-driven approaches to identify sectors and regions where credit can have the greatest economic impact.
He pointed to portfolio-based lending and digital technologies, including Internet of Things (IoT) systems and blockchain, as tools that could allow banks to monitor borrowers more efficiently without depending entirely on frequent physical inspections.
Thewarathanthri also noted that banks and non-bank financial institutions already provide some forms of collateral-free financing through programme-based lending and community cross-guarantees. He said Sri Lanka’s state-backed credit guarantee mechanism was gaining momentum, although he did not have figures on its overall uptake.
The National Credit Guarantee Institution (NCGI), which began operations in January 2025, had issued its 2,000th guarantee by July 2026, facilitating more than Rs.14 billion in SME credit. The institution has said it aims to expand its reach further, with the government also looking to strengthen areas including development banking and alternative financing mechanisms. Newswire
Thewarathanthri further called for a more targeted approach to agricultural financing. He argued that funding for specialised crops should be concentrated in suitable geographical areas so that supporting infrastructure such as collection centres, warehouses and transportation networks can develop around production regions.
He warned that poorly targeted agricultural lending could result in large numbers of farmers producing the same crops without sufficient market demand. This could ultimately push down farm-gate prices and leave growers struggling to sell their harvests.
The discussion also touched on directed lending and the role of the Central Bank. Thewarathanthri compared Sri Lanka’s agricultural lending requirement with India’s priority-sector lending framework, while noting that the two systems are not directly comparable.
He pointed out that India’s broader priority-sector target covers multiple categories, while Sri Lanka’s cited 10 percent requirement relates specifically to agriculture. India also maintains a separate agriculture sub-target, making the comparison more specific when looking at agricultural lending alone.
He said mechanisms used in India, including requirements for banks that fall short of lending targets to contribute to designated development funds, could provide areas for Sri Lanka to consider.
Agriculture was presented as a particularly important area for development finance. Thewarathanthri highlighted the sector’s role in employment and argued that increasing agricultural productivity and value addition could help raise rural incomes.
Official data from Sri Lanka’s Department of Census and Statistics show that agriculture accounted for 8.4 percent of GDP in the second quarter of 2026, while 23.7 percent of the workforce was employed in the sector during the first quarter. Overall economic activity expanded by 4.2 percent in the second quarter, although agricultural activity contracted during the period. Sri Lanka Statistics
Thewarathanthri argued that increasing agriculture’s contribution to the economy would require greater use of technology and mechanisation. He referred to tools such as geo-fencing, climate forecasting and crop monitoring, while noting that technology solutions need to be designed around Sri Lanka’s relatively small farm sizes.
He also identified export opportunities for agricultural products including coconut, cinnamon, fruits and organic produce, particularly in markets such as the UAE and Singapore.
Food security was another major consideration raised during the discussion. Thewarathanthri linked Sri Lanka’s dependence on agricultural imports and international food supply chains to broader economic and national security concerns, particularly amid disruptions to global trade.
He argued that improving domestic agricultural productivity should therefore be considered alongside the country’s wider development and growth objectives.
At the same time, DFCC Bank Director and Chief Executive Officer Thimal Perera highlighted the importance of ensuring that any future development bank operates independently and without political interference.
Perera cautioned that a development bank that consistently operates at a loss could ultimately become a financial burden on taxpayers. He also pointed to DFCC’s own history, noting that Sri Lanka’s first development bank eventually shifted towards commercial banking after six decades, partly because of difficulties in securing long-term funding at affordable costs.
The contrasting perspectives underline the broader challenge facing Sri Lanka as it considers the future of development banking: expanding access to long-term finance for SMEs and priority sectors while ensuring that institutions can attract capital, operate sustainably and direct funding towards areas capable of generating wider economic benefits.
Image Disclaimer: Pictures used in this article belong to their rightful owners.