- Insists 5% target gave room to look through Middle East supply shock
- Warns shift to 2% would shave 3 points off nominal GDP growth, strain debt ratios
- Rules out quick move to lower target, says peers took 10 to 25 years
The Central Bank on Friday defended its decision to retain the 5 percent inflation target even as inflation runs at 8 percent, with senior officials asserting that a 2 percent target would have forced far steeper interest rate hikes than the 100 basis points delivered in May, at the expense of growth and public debt.
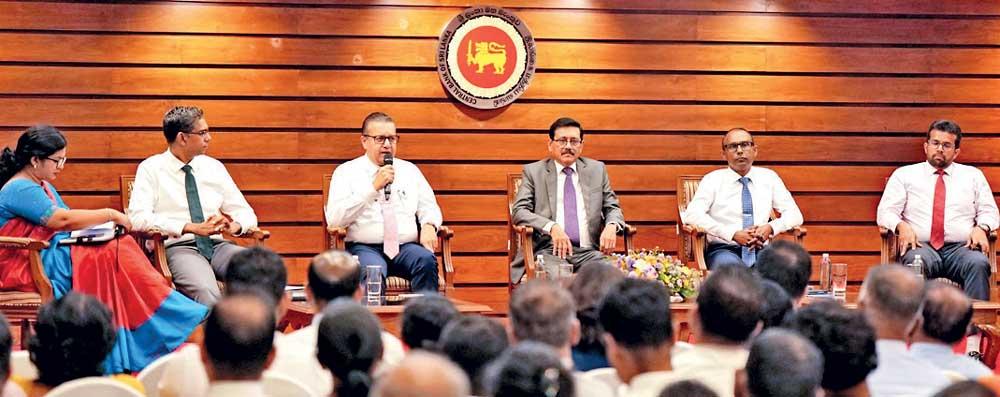
The officials were speaking at a panel discussion held to explain the first scheduled review of the target, which concluded with the President, in his capacity as Finance Minister, and the Central Bank Governor signing a new Monetary Policy Framework Agreement on October 1 that retains the 5 percent target and the accountability margin of plus or minus 2 percentage points for three more years.
Headline inflation, as measured by the Colombo Consumer Price Index, accelerated to 8 percent in September from 2.2 percent in March, leaving it 3 percentage points above the target and a full percentage point beyond the upper edge of the margin.
Justifying the measured response to the overshoot, Central Bank Economic Research Director Dr. Lasitha Pathberiya attributed the acceleration to the Middle East conflict, which lifted diesel prices by 40 percent between March and August, and insisted that the 5 percent target had allowed the Monetary Policy Board to look through part of the supply shock.
“If we had an inflation target of 2 percent at that time, then our response would have been much, much higher than a 1 percent increase. That is the cost to the economy,” he stressed.
He further warned that moving to 2 percent would reduce nominal GDP growth by 3 percentage points in the steady state, weighing on public debt as a share of GDP, and could therefore not be done overnight.
Dr. Pathberiya also countered that the 2 percent target, which featured in public debate ahead of the review, is largely an advanced economy practice. Of roughly 50 inflation targeting countries studied, 15 target 2 percent and 13 of those are advanced economies, while about a third of emerging economies target 5 percent or more, he pointed out.
Meanwhile, Central Bank Senior Economist and Modelling and Forecasting Division Head Dr. Vishuddhi Jayawickrema backed that position, warning that disinflation carries a measurable price and citing research that places the output loss in developing and emerging economies between half a percentage point and 3 percentage points for every 1 percentage point reduction in inflation.
“A lower inflation target could be good news in the long run, but it could be bad news if we try to achieve it too quickly,” he remarked, adding that slower economic activity would also drag down nominal wage growth and new hiring.
Central Bank Governor Dr. Nandalal Weerasinghe rejected the argument that a lower target would leave households better off, maintaining that it might appear better for purchasing power but would hold growth below potential, leaving more people worse off.
“It cannot be 5 to 2 percent. That is a huge adjustment that I don’t think any country in the world will do. It has to be gradual,” he emphasised.
Central Bank Assistant Governor Dr. P.K.G. Harischandra played down the prospect of an early shift to a lower target, pointing out that countries such as Brazil, the Philippines and Indonesia spent around 10 to 15 years, and in some cases over 25 years, bringing their targets down from the 5 to 8 percent range to 2 to 3 percent. He anticipated that Sri Lanka would follow a similar path, with the target easing to 4 percent and later to 3 percent as the economy matures.
Blames ‘bad luck, not bad policy’ for missing target
The Central Bank has missed its inflation target for most of the three years since flexible inflation targeting was written into law, largely on account of external shocks and not policy error, a senior official conceded on Friday.
“During that period, unfortunately, we missed the target most of the time. That is not because of bad policy. That is because of bad luck, I would say,” Central Bank Assistant Governor Dr. P.K.G. Harischandra remarked at the panel discussion on the inflation target review, referring to the period since the Central Bank Act was enacted in 2023.
Inflation has swung from 11 consecutive months of deflation, which bottomed out at around minus 4 percent, to 8 percent in September, a range of about 12 percentage points around a target of 5 percent, as per figures cited by Governor Dr. Weerasinghe.
The framework requires the Monetary Policy Board to report to Parliament through the Finance Ministry whenever inflation stays above 7 percent or below 3 percent for two consecutive quarters, a step the Central Bank already took during the deflationary episode.
However, Dr. Harischandra argued that the framework must be allowed to perform for some time in order to build a track record of delivery, while the Governor acknowledged where the burden lies.
“If we fail to deliver, that is our problem. That is a credibility issue,” Dr. Weerasinghe noted.